Key Takeaways
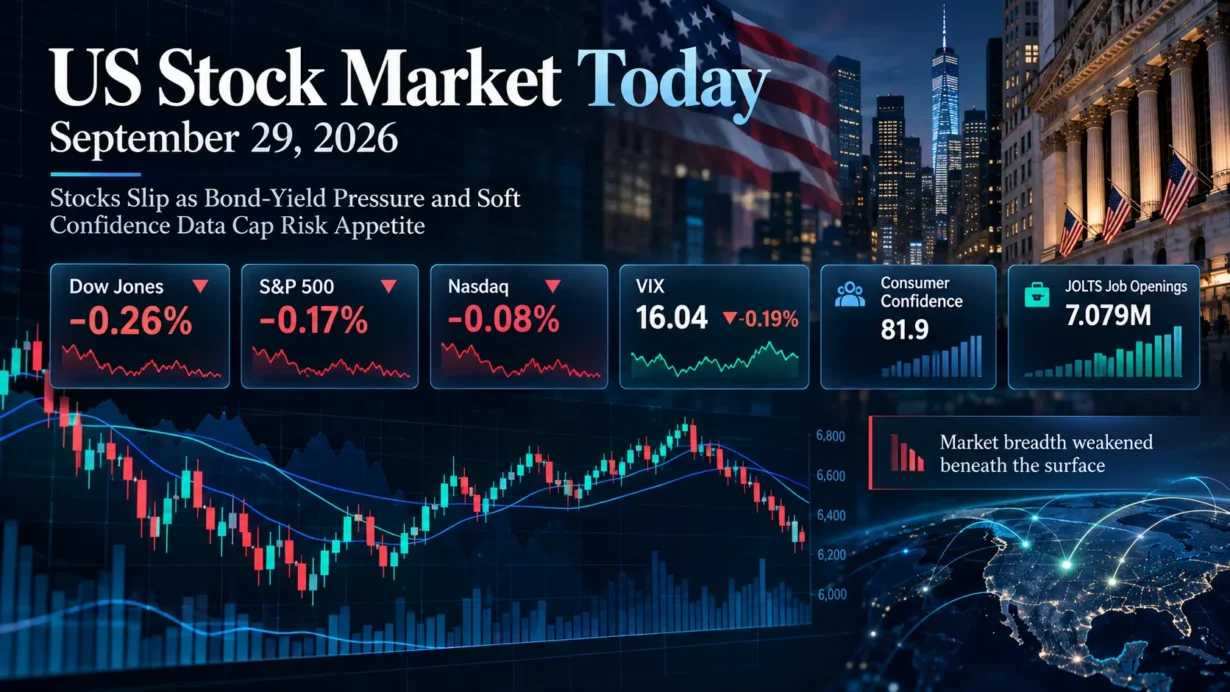
- The Dow Jones Industrial Average fell 0.26% to 51,349.92, the S&P 500 lost 0.17% to 7,670.84, and the Nasdaq Composite slipped 0.08% to 26,797.54. The Russell 2000 declined 0.35% to 2,807.92, leaving small caps weaker than large caps.
- Utilities led the S&P 500 sectors with a 1.14% gain, while Energy fell 0.89% and ranked last as crude oil retreated. Negative breadth was more severe than the headline index moves: decliners outnumbered advancers 1.66-to-1 on the NYSE and 1.47-to-1 on Nasdaq.
- The Treasury curve steepened. In late New York trading, the 2-year yield fell 3.51 basis points to 4.889%, while the 10-year rose 1.32 basis points to 5.255% after reaching 5.2932% intraday, its highest level since June 2007.
- Macro data reinforced a difficult growth-inflation mix: August JOLTS job openings fell to 7.079 million, below the 7.225 million Reuters consensus, while the Conference Board Consumer Confidence Index dropped to 81.9 from 88.6 in August.
- Stock-specific dispersion was extreme. CarMax rose 4.74% after stronger fiscal second-quarter results and improving operating leverage, while Fair Isaac fell 26.5% as investors repriced competitive risk in mortgage credit scoring.
1. Market Capital Flows and Sector Rotation:
Sector leadership was defensive but not broadly risk-off. Utilities gained 1.14%, the best performance among the 11 S&P 500 sectors, while Energy fell 0.89% and finished last as oil prices reversed lower. Large caps held up better than small caps: the S&P 500 declined 0.17% versus a 0.35% drop in the Russell 2000. The growth-versus-value signal was less clean. The growth-heavy Nasdaq Composite outperformed the Dow on the downside, but the session did not resemble a broad duration-led growth rally because long Treasury yields remained elevated. The more useful read is that investors favored selected mega-cap and defensive exposures while cutting risk more aggressively in smaller companies and oil-sensitive cyclicals.
Internal breadth was materially weaker than the index tape. Reuters closing data showed decliners leading advancers by 1.66-to-1 on the NYSE and 1.47-to-1 on Nasdaq. The S&P 500 recorded eight new 52-week highs against 33 new lows, while the Nasdaq Composite posted 34 new highs against 244 new lows. U.S. exchange volume totaled 16.15 billion shares, below the 20-session average of 16.87 billion. That combination suggests the modest index decline understated the pressure beneath the surface, although the below-average volume argues against characterizing the session as capitulation.
Institutional Flow Insight: A plausible, but not directly observable, institutional explanation is a simultaneous adjustment to duration risk and equity risk budgets. Higher long-end yields raise discount rates and financing costs, which can encourage portfolios to favor earnings visibility and lower-beta exposures, while the oil reversal removed a near-term catalyst from Energy. Utilities may also have attracted relative-value and defensive demand after prior rate-driven weakness. With quarter-end one session away, rebalancing could have amplified some moves, but there is no verified flow dataset here proving that quarter-end activity was the primary driver.
2. Decoding the Biggest Market Movers:
CarMax (KMX)
CarMax closed at $59.23, up 4.74%. The move was supported by operating results rather than a purely technical squeeze. In its official fiscal Q2 2027 release, CarMax reported total net revenue of $7.9 billion, up 19.5% year over year, while combined retail and wholesale unit sales increased 14.7% to 387,735. Retail used-unit sales rose 13.8%, comparable-store used-unit sales increased 13.0%, and diluted EPS rose to $1.16 from $0.64, an 81.3% increase. CarMax Auto Finance income increased 32.1% to $135.6 million, while SG&A expense rose 4.6% to $628.6 million and improved by $157, or 8.8%, per total unit. The company also said it plans to resume share repurchases in fiscal Q3.
The earnings quality deserves a more nuanced read than the headline EPS growth. Retail gross profit per used unit was $2,105, down $111 year over year, reflecting deliberate pricing actions designed to support unit growth. Wholesale gross profit per unit fell $135 to $858. On the earnings call, management said full-year FY2027 retail gross profit per unit is expected to decline by less than $200 versus FY2026 and indicated that year-over-year pressure should continue in the third and fourth quarters. At the same time, Extended Protection Plan margin per retail unit rose $46 to $623, and management maintained an expectation of roughly $35 per unit of incremental EPP margin for the full fiscal year.
The read-through for Consumer Discretionary is therefore company-specific rather than a clean macro bullish signal. CarMax is showing that sharper pricing can unlock volume even as consumer confidence deteriorates, but the trade-off is lower vehicle gross profit per unit. For the stock to sustain a higher valuation, investors will likely focus on whether unit growth, SG&A leverage, financing income and ancillary-product economics can continue to offset the margin investment. The same framework matters for used-auto peers: share gains achieved through price can be valuable, but only if operating leverage preserves enterprise-level profitability.
Fair Isaac (FICO)
Fair Isaac fell 26.5% in regular trading, one of the session’s largest S&P 500 declines. The immediate catalyst was a further repricing of competition risk in mortgage credit scoring. Fannie Mae had already announced on September 9 that VantageScore 4.0 was broadly available to approved lenders as an alternative to eligible Classic FICO scores. The fresh market trigger was Federal Housing Finance Agency Director Bill Pulte’s statement that Fannie Mae and Freddie Mac would move toward a single mortgage pricing grid as VantageScore gains broader use.
The distinction matters: this was not an earnings miss, and Classic FICO remains an eligible option under Fannie Mae’s published framework. The stock reaction instead reflects a sharp reset in assumptions around FICO’s competitive moat and long-run pricing power in a market where institutional standards historically supported very high switching costs. For software and data-service investors, the broader lesson is that regulatory or standards-setting changes can compress valuation multiples even when current-period financial results are unchanged. The move should not, however, be treated as evidence of a broad software selloff; it was primarily an idiosyncratic policy-and-competition shock.
3. Macro Indicators and Market Outlook
The Cboe VIX closed at 16.04, down 0.03 point, or 0.19%, from the prior close. That was directionally inconsistent with the modest equity decline and the weak breadth, which is informative. Options markets did not register a broad volatility shock even as more stocks fell than rose. The better interpretation is that investors were reducing exposure selectively and repricing interest-rate sensitivity rather than paying aggressively for index-level crash protection. A sustained VIX move higher alongside weaker breadth would represent a more consequential deterioration in risk appetite than Tuesday’s close alone.
Treasuries carried the more important cross-asset signal. In late New York trading, the 2-year yield was 4.889%, down 3.51 basis points, while the 10-year yield was 5.255%, up 1.32 basis points after an intraday high of 5.2932%. The curve therefore steepened as the front end eased while the long end remained under pressure. The move is consistent with investors separating near-term Federal Reserve policy expectations from longer-horizon inflation, supply and term-premium risks. It would be inappropriate to translate one day’s yield changes into a certain rate-hike or rate-cut outcome; the curve instead shows that long-duration assets still face a high discount-rate hurdle even as the market reassesses the timing of the next Fed move.
Macro data added to that tension. The Bureau of Labor Statistics reported 7.079 million job openings in August, down 256,000 from July, while hires were little changed at 5.2 million and layoffs remained low. Separately, the Conference Board Consumer Confidence Index fell 6.7 points to 81.9, with both current-condition and expectations measures deteriorating. Softer labor demand and weaker sentiment would normally argue for less policy pressure, but elevated energy costs and persistent inflation concerns have kept the long end sensitive to inflation risk. Oil’s retreat on Tuesday helped Energy underperform and reduced some immediate inflation pressure, but it did not erase the broader rate problem for equity valuations.
Upcoming Economic Data & Catalysts:
- BEA Personal Income and Outlays, August 2026 (Release date: September 30, 2026): Investors will focus on the PCE price indexes, income growth and real consumer spending. Inflation persistence would matter directly for Treasury term premia and equity discount rates, while spending data will help test whether weak confidence is translating into softer demand.
- BLS Employment Situation, September 2026 (Release date: October 2, 2026): Payroll growth, the unemployment rate and wage growth will be central to the market’s assessment of labor-market resilience and the policy path. A materially different labor signal from JOLTS could quickly reprice both the front end of the Treasury curve and rate-sensitive equity multiples.
Market Insights:
The session was not a classic broad risk-off liquidation. Headline indexes fell only modestly and the VIX edged lower, but breadth was decisively negative and small caps underperformed. That points to a market being held together by selective large-cap resilience rather than broad participation. The current setup would become more fragile if the 10-year yield establishes new highs, breadth continues to deteriorate, earnings estimates are revised lower, or volatility rises while index leadership narrows further. Conversely, stabilization in long yields combined with improving advance-decline data would provide stronger confirmation that risk appetite is broadening.
Trading & Investment Strategy:
Risk control should take priority over chasing single-session gaps. Position sizes should reflect the unusually high sensitivity of equity valuations to Treasury yields, and new exposure can be staged rather than entered all at once ahead of PCE and payroll data. Sector selection should distinguish between durable earnings visibility and temporary defensive rotation, while company-specific winners such as CarMax still require scrutiny of unit economics after a sharp price move. Predetermined maximum-loss or exit levels should be calibrated to each security’s volatility and liquidity rather than using a universal percentage. Investors should also avoid adding leverage simply because the VIX remains subdued; weak breadth can deteriorate before headline volatility catches up.
4. Key FAQs About the US Stock Market Today
Why did the US stock market move on September 29, 2026?
U.S. stocks slipped as long-term Treasury yields stayed near multi-decade highs, raising the discount rate applied to equities, while weaker JOLTS job openings and a sharp drop in consumer confidence reinforced growth concerns. The major indexes recovered from deeper intraday losses after shorter-term yields eased, but negative breadth showed that the pressure was broader than the small headline index declines suggested. Company-specific moves, including CarMax’s post-earnings rally and FICO’s policy-driven plunge, added unusually high single-stock dispersion.
Which sectors performed best and worst in the US stock market on September 29, 2026?
Utilities was the best-performing S&P 500 sector, gaining 1.14%, while Energy was the worst, falling 0.89%. The rotation favored selected defensive exposure as investors managed rate and growth risk, while Energy weakened alongside a pullback in crude oil. Because the VIX did not rise and small caps lagged, the session is better described as selective de-risking and factor rotation than a uniform flight to safety.
What should investors watch after the US stock market close on September 29, 2026?
The immediate macro focus is the September 30 BEA Personal Income and Outlays report, including PCE inflation, followed by the September Employment Situation on October 2. Investors should also monitor whether the 10-year Treasury yield can stay below Tuesday’s intraday high near 5.293%, whether market breadth improves from the day’s negative readings, and whether the VIX begins to confirm the deterioration seen beneath the headline indexes. Corporate guidance and earnings revisions remain important because elevated yields leave less valuation room for companies that miss cash-flow expectations.
Disclaimer: This article is intended solely for the exchange of investment ideas and does not constitute investment advice of any kind.