
Key Takeaways
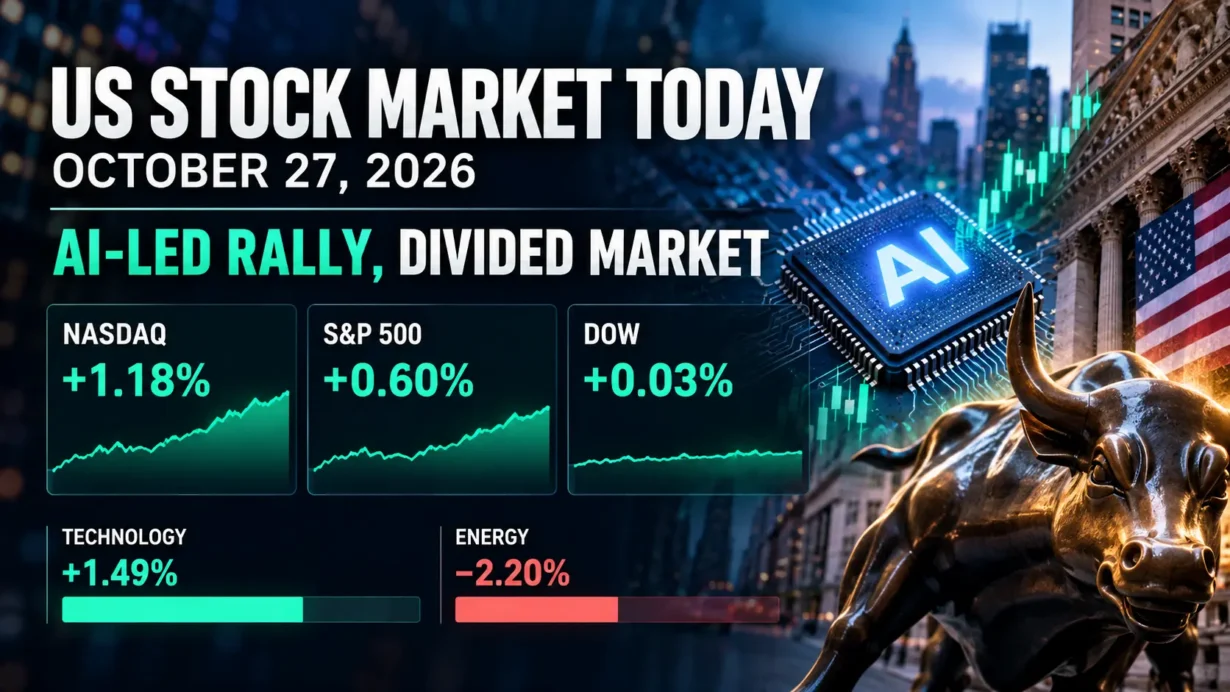
- The S&P 500 gained 0.60% to 7,722.60; the Nasdaq Composite rose 1.18% to 26,477.81. The Russell 2000 climbed 1.16% to 2,818.87, while the Dow barely advanced, up 0.03% to 52,377.57.
- Within the S&P 500, information technology led at +1.49%, while energy fell 2.20%. Broadcom gained 4.00% on AI infrastructure financing news; Boeing lost 10.69% following its earnings call.
- September durable-goods orders increased 1.8% month over month, while the Conference Board’s October consumer-confidence index rose to 91.7 from a revised 84.2 in September.
- The Cboe VIX fell 0.87 point to 17.52; the two-year Treasury yield rose 2 basis points to 4.70%, while the 10-year slipped 1 basis point to 4.99%, ahead of the October 28 Fed decision.
1. Market Capital Flows and Sector Rotation
Tuesday’s advance was led by earnings visibility rather than uniform enthusiasm for risk. The S&P 500 information technology sector gained 1.49%, followed by consumer discretionary (+1.36%) and materials (+0.78%). Energy was the weakest sector at -2.20%, followed by real estate (-0.91%) and consumer staples (-0.90%). Utilities rose 0.70%, showing that defensives were not uniformly sold. Falling crude prices pressured energy, while AI infrastructure demand supported technology. These are S&P 500 sector-index moves, not ETF returns. Sources: October 27 sector-index closing data and Reuters’ closing report.
Growth-oriented technology outpaced the value-heavy Dow, but cyclicals diverged: consumer discretionary and materials advanced as energy and financials (-0.27%) lagged. Small caps participated, with the Russell 2000 outperforming the S&P 500 by 0.56 percentage point. Market breadth was more nuanced than the headline: most S&P 500 constituents declined, even as advancing issues outnumbered decliners by 1.83-to-1 on the NYSE and 1.86-to-1 on Nasdaq. U.S. exchange volume totaled 16.10 billion shares, below the 20-session average of 17.18 billion. The distinction matters: index concentration remained evident, but exchange-wide participation was not uniformly weak. Sources: Associated Press and Reuters.
Institutional Flow Insight: The relative strength of semiconductors and selective cyclicals is consistent with investors favoring visible AI-related spending and company-specific execution over a broad value or defensive rotation. Lower implied volatility may have eased risk-budget pressure, while elevated yields still challenge rate-sensitive valuations. These are plausible allocation explanations, not verified institutional trading flows; there is no basis to attribute the move definitively to month-end rebalancing.
2. Decoding the Biggest Market Movers
Broadcom (AVGO)
Broadcom finished the regular session up 4.00%. A company-posted announcement dated October 26 detailed a $63 billion financing structure arranged with Bank of America, Blackstone, Citi and Morgan Stanley to fund purchases of Broadcom AI accelerators and networking products for lease to Anthropic. Deliveries under the broader agreement are expected to start in calendar 2027. Importantly, Broadcom provides residual-value support tied to the first-lien financing; the transaction is neither $63 billion of immediately recognized revenue nor free of balance-sheet risk.
For context—not as new October 27 earnings—Broadcom’s latest fiscal Q3 report, released September 2, recorded $29.591 billion in revenue, including $16.7 billion of AI semiconductor revenue, GAAP diluted EPS of $2.68 and non-GAAP diluted EPS of $3.32. Management described a roughly 68% non-GAAP operating margin on its Q3 earnings call; its published fiscal Q4 guidance was approximately $34.8 billion in revenue and non-GAAP operating income equal to approximately 66% of revenue. Those figures are management guidance, not realized Q4 results. The October financing news reinforced demand visibility for custom AI silicon, but also focused attention on customer financing and asset-residual exposure.
Boeing (BA)
Boeing dropped 10.69% despite third-quarter revenue rising 4% year over year to $24.188 billion. Its October 27 earnings release reported a GAAP diluted loss of $0.26 per share, a non-GAAP core loss of $0.34 per share, GAAP operating margin of 1.5%, core operating margin of 0.8%, and positive non-GAAP free cash flow of $464 million. The earnings-call transcript showed why the stock struggled: management said production was not yet stable at 47 737 jets per month and targeted 52 per month only in the second half of 2027. Its approximately $3 billion 2027 free-cash-flow figure is a management target, not current cash generation.
The comparison is revealing: Broadcom’s financing framework strengthened confidence in future compute deployment, while Boeing’s $745 billion backlog did not shield its shares from a slower conversion of orders into production and cash. That execution-versus-demand divide helps explain why technology led while the Dow barely rose, even though the broader industrials sector advanced 0.58%.
3. Macro Indicators and Market Outlook
The Cboe VIX closed at 17.52, down 0.87 point, or 4.73%. Lower option-implied volatility was consistent with the equity advance, but it does not prove hedging demand disappeared—particularly with the Fed decision and megacap earnings still ahead.
On the Treasury’s official October 27 daily par-yield curve, the two-year yield was 4.70% (+2 basis points) and the 10-year was 4.99% (-1 basis point). The 10-year minus two-year spread narrowed 3 basis points to 29 basis points. This modest flattening suggests differentiated pricing of near-term policy versus longer-run growth and term-premium risks; it does not establish the Fed’s next move. The prevailing federal funds target range before the meeting was 3.75%-4.00%.
The latest macro releases supplied a growth counterweight to rate anxiety: Census Bureau data showed September durable-goods orders up 1.8%, or 0.5% excluding transportation, while the Conference Board reported October consumer confidence at 91.7. Resilient demand can support earnings while also reducing the room for a dovish policy surprise.
Upcoming Economic Data & Catalysts:
- Federal Open Market Committee rate decision and press conference (Release date: October 28, 2026): The 2:00 p.m. ET decision and 2:30 p.m. ET press conference will be assessed for the policy path, inflation risks and financial-conditions implications.
- BEA third-quarter GDP advance estimate and September personal income and outlays (Release date: October 29, 2026): Both scheduled for 8:30 a.m. ET, these releases will inform growth expectations and the inflation picture, including the personal consumption expenditures price measures.
Market Insights:
October 27 was primarily an AI-led, capitalization-sensitive advance—not an unqualified broad-market breakout. Positive exchange-level breadth and Russell 2000 strength complicate a purely narrow-market narrative, but sector dispersion remains substantial. A sustained rise above 5% in the 10-year yield, weaker participation, downward earnings revisions, unexpected Fed communication or a reversal in volatility could challenge leadership; these are risk scenarios, not forecasts.
Trading & Investment Strategy:
Size positions against portfolio drawdown limits and event risk rather than recent price momentum. Stagger entries instead of chasing semiconductor strength immediately before major releases; balance exposures across earnings-resilient sectors and avoid treating weak energy or aerospace names as automatic bargains. Use predefined, volatility-aware exit levels, review position concentration, and maintain liquidity for potential post-Fed repricing. No single-session pattern guarantees a durable trend.
4. Key FAQs About the US Stock Market Today
Why did the US stock market move on October 27, 2026?
AI semiconductor buying, highlighted by Broadcom’s Anthropic-related financing announcement, lifted the Nasdaq and S&P 500. Stronger durable-goods orders and consumer confidence helped offset rate uncertainty, while Boeing’s production outlook weighed on the Dow.
Which sectors performed best and worst in the US stock market on October 27, 2026?
S&P 500 information technology led at +1.49%, followed by consumer discretionary at +1.36%. Energy was weakest at -2.20% as crude prices declined; real estate and consumer staples also lagged. These figures refer to sector indices, not sector ETFs.
What should investors watch after the US stock market close on October 27, 2026?
Watch the October 28 Fed decision and communication, October 29 GDP and personal-income releases, Treasury yields near 5%, and whether technology leadership broadens as major company earnings arrive. Treat any breakout cautiously if market breadth deteriorates.
Disclaimer: This article is intended solely for the exchange of investment ideas and does not constitute investment advice of any kind.