
Key Takeaways
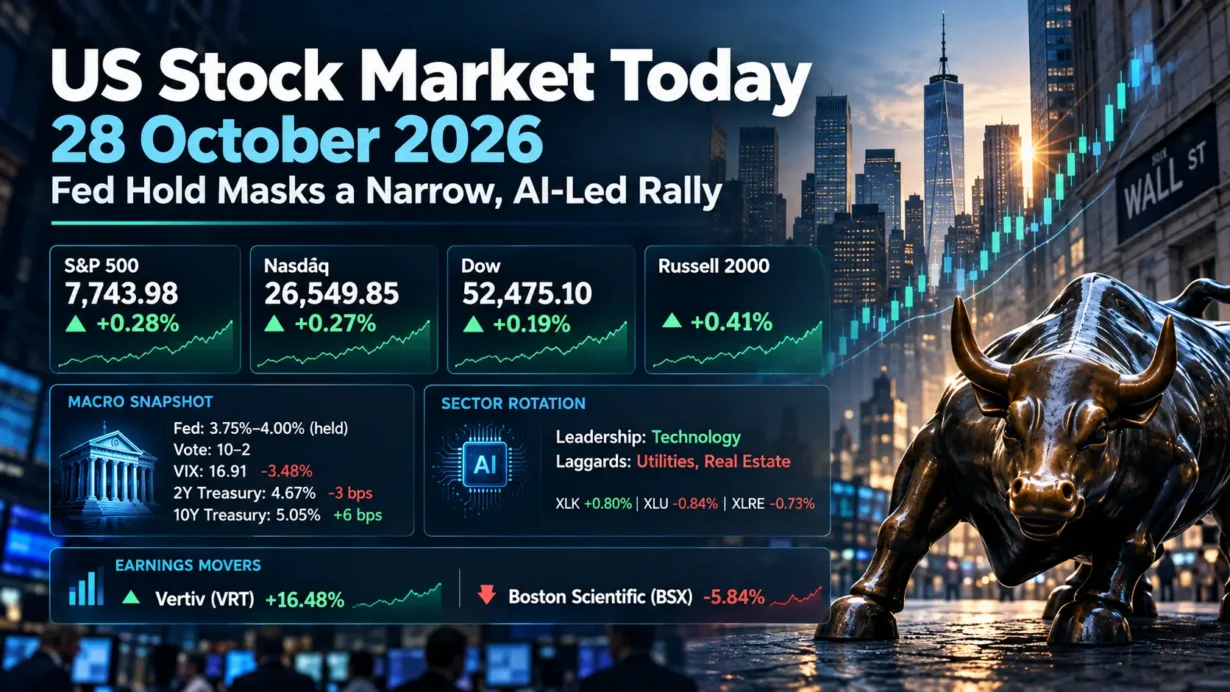
- U.S. equities closed higher in the regular session: the S&P 500 rose 0.28% to 7,743.98, the Nasdaq Composite gained 0.27% to 26,549.85, and the Dow advanced 0.19% to 52,475.10. The Russell 2000 added 0.41%.
- The Federal Reserve held its policy-rate range at 3.75%–4.00% by a 10–2 vote; both dissenters preferred a 25-basis-point increase, underscoring persistent inflation risk.
- Technology led while rate-sensitive defensives lagged: XLK rose 0.80%, versus declines of 0.84% for XLU and 0.73% for XLRE. These are sector ETF price returns, not official S&P 500 sector-index returns.
- Vertiv jumped 16.48% on stronger reported results and higher company guidance; Boston Scientific fell 5.84% amid weaker growth and a cybersecurity-related earnings headwind.
- The VIX fell to 16.91, but the Treasury curve steepened: the two-year yield declined to 4.67%, while the 10-year yield rose to 5.05%.
1. Market Capital Flows and Sector Rotation
The closing tape favored businesses with visible earnings growth over conventional interest-rate-sensitive exposures. Among the Select Sector SPDR ETFs, technology (XLK) was the strongest at +0.80%, followed by financials (XLF) at +0.45% and energy (XLE) at +0.35%. Utilities (XLU) were weakest at −0.84%, followed by real estate (XLRE) at −0.73%; communication services (XLC) fell 0.42% and consumer staples (XLP) lost 0.36%. These figures measure October 28 regular-session ETF share-price changes and serve only as transparent proxies for sector performance; ETF returns can differ from official S&P 500 sector-index returns. Sources: XLK, XLF, XLE, XLU, XLRE and XLC historical prices.
Style and size signals were mixed rather than uniformly risk-on. The Russell 2000’s +0.41% gain exceeded the cap-weighted S&P 500’s +0.28%, suggesting some small-cap participation. Yet the cap-weighted S&P 500 ETF (SPY) rose 0.34% while the equal-weight S&P 500 ETF (RSP) slipped 0.04%, a warning that strength was uneven within large caps. Growth-oriented technology led, but financials and energy showed selective cyclical and value participation. Defensive staples and utilities lagged, although health care was not uniformly weak. Sources: AP closing index report, SPY and RSP.
Institutional Flow Insight: This pattern is consistent with investors prioritizing earnings visibility and AI-infrastructure demand while limiting exposure to assets vulnerable to higher long-term discount rates. The rise in the 10-year Treasury yield offers a plausible explanation for pressure on utilities and real estate; elevated valuations and policy uncertainty still constrain risk budgets. Late-month portfolio rebalancing could also have influenced trading, but public price data cannot establish actual institutional purchases, sales or rebalancing activity.
2. Decoding the Biggest Market Movers
Vertiv Holdings (VRT)
Vertiv surged 16.48% to $242.94 at the 4:00 p.m. ET close. Its October 28 earnings release, also filed with the SEC, reported third-quarter net sales of $4.313 billion, up 61% year over year, including 55% organic growth. GAAP diluted EPS reached $1.95; adjusted diluted EPS was $2.21, up 78%. Adjusted operating margin expanded 290 basis points to 25.2%, and organic orders more than doubled. Management raised its full-year 2026 guidance to $14.45 billion–$14.85 billion in net sales and $7.10–$7.20 in adjusted diluted EPS; these are company projections, not achieved results. On the earnings call, the CFO said approximately $100 million–$150 million of revenue delayed from the second quarter was recognized in the third, a qualification against mechanically annualizing the quarterly growth rate (third-party call transcript). The investment read-through extends beyond one industrial stock: spending on power and cooling for AI data centers can support a different earnings stream from semiconductor or cloud-software exposure, although execution and valuation risks remain. Regular-session closing-price source.
Boston Scientific (BSX)
Boston Scientific declined 5.84% to $42.43 at the regular-session close. Its official third-quarter release and matching SEC exhibit showed sales of $5.138 billion, up only 1.5% organically and on a reported basis. GAAP EPS fell to $0.40 from $0.51, while adjusted EPS declined to $0.73 from $0.75. Management identified a cybersecurity incident as a disruption and issued full-year 2026 guidance for approximately 3.75% organic sales growth and adjusted EPS of $3.16–$3.18. Its fourth-quarter outlook called for a 1%–3% organic sales decline. During the call, management estimated the incident reduced third-quarter revenue by approximately $150 million and adjusted EPS by $0.07 (third-party call transcript). The selloff highlights how quickly a premium medtech growth narrative can reprice when operating reliability and near-term forecasts deteriorate; it does not, by itself, establish weakness across the entire health-care sector. Regular-session closing-price source.
Methodology note: Company revenue, EPS, margins and guidance above are taken from issuer releases and SEC filings. Earnings-call commentary is separately attributed to third-party written transcripts; the issuers’ official investor materials provide webcast access rather than a verified issuer-published written transcript.
3. Macro Indicators and Market Outlook
The Cboe Volatility Index finished October 28 at 16.91, down 0.61 point, or 3.48%, from 17.52. Falling 30-day implied S&P 500 volatility was directionally consistent with rising equity benchmarks and less expensive near-term option protection. It is not evidence that geopolitical, earnings or macroeconomic event risks have disappeared.
On the U.S. Treasury’s official daily par-yield curve, the two-year yield ended at 4.67%, down 3 basis points from October 27, while the 10-year yield rose 6 basis points to 5.05%. The 10-year minus two-year spread widened from 29 to 38 basis points. The front-end decline and long-end increase suggest divergent repricing of near-term policy expectations versus longer-duration inflation, supply and term-premium risks; one session cannot identify the precise contribution of each. In its October 28 statement, the Fed held its target range at 3.75%–4.00% by a 10–2 vote, described economic activity as expanding strongly and inflation as elevated, and recorded two votes in favor of a quarter-point hike. This is a restrictive policy backdrop, not confirmation of a specific future rate path.
Renewed Middle East supply concerns also pushed oil prices higher, reinforcing the potential tension between energy-sector earnings and broader inflation-sensitive equity valuations. That backdrop makes the 10-year yield more consequential than the small positive index returns alone would suggest. Source: Reuters oil-market report.
Upcoming Economic Data & Catalysts:
- U.S. Real Gross Domestic Product, Third Quarter 2026 (Advance Estimate) (Release date: October 29, 2026, 8:30 a.m. ET): The first official growth estimate will test the resilience embedded in the Fed’s assessment and could influence cyclical earnings expectations and longer-term yields.
- U.S. Personal Income and Outlays, September 2026 (Release date: October 29, 2026, 8:30 a.m. ET): The personal consumption expenditures inflation readings and consumer spending data will inform the policy and discount-rate debate.
Both releases appear on the Bureau of Economic Analysis’ official release calendar and were still upcoming as of the October 28 market close.
Market Insights: Wednesday’s advance was selective, not a clean broad-market breakout: cap-weighted gains and technology leadership contrasted with a slightly negative equal-weight ETF, even as small caps participated. Confirmation would require improving breadth alongside durable earnings revisions. A further spike in long-term yields, disappointing AI spending returns, weaker corporate guidance, renewed inflation pressure or a reversal higher in implied volatility could interrupt the move. Microsoft and Alphabet reported results after the closing bell; those releases are subsequent catalysts, not drivers of the 4:00 p.m. closing prints.
Trading & Investment Strategy: Maintain position sizes consistent with a defined portfolio risk budget, rather than using the index’s modest gain to justify indiscriminate exposure. Stagger entries in earnings-backed opportunities, diversify AI exposure across suppliers and end markets, and assess valuation sensitivity to a 10-year yield above 5%. Avoid chasing outsized single-day earnings gaps; establish downside exit or rebalancing levels before initiating positions, monitor equal-weight breadth and implied volatility, and allow Thursday’s scheduled data to clarify the rate backdrop. No single signal guarantees a favorable outcome.
4. Key FAQs About the US Stock Market Today
Why did the US stock market move on October 28, 2026?
The major indexes edged higher after a widely anticipated Fed hold, supported by selected technology and AI-infrastructure earnings. Two dissenting votes for a rate increase, rising 10-year yields and uneven participation prevented the session from becoming a broad risk-on rally.
Which sectors performed best and worst in the US stock market on October 28, 2026?
Based on regular-session Select Sector SPDR ETF price returns, technology was strongest (XLK +0.80%), followed by financials (XLF +0.45%); utilities (XLU −0.84%) and real estate (XLRE −0.73%) were weakest. The spread was consistent with preference for visible growth and selective cyclicals over rate-sensitive defensives, though these are ETF proxies rather than official sector-index returns.
What should investors watch after the US stock market close on October 28, 2026?
Watch the BEA’s October 29 GDP and September personal income and outlays releases, the direction of the 10-year yield and the S&P 500’s equal-weight breadth. The market reaction to post-close megacap earnings will also help determine whether AI-led performance can broaden without added valuation pressure.
Disclaimer: This article is intended solely for the exchange of investment ideas and does not constitute investment advice of any kind.